Introduction to liability insurance needs for lacrosse teams
As any passionate lacrosse player knows, the fast-paced game comes with its fair share of bumps, bruises, and potential injuries. From errant stick checks to collisions going for ground balls, accidents can and do happen. This makes having proper insurance coverage absolutely essential for teams at every level.
While recreational leagues may get by with basic accident coverage, more competitive club and travel teams need robust liability protection. A lawsuit stemming from a serious injury could financially cripple a team without the right insurance.
But securing coverage isn’t always easy or straightforward. Between excluded activities, high deductibles, and excluded parties, many plans leave major gaps. And terms like “occurrence” versus “claims made” policies can confuse coaches and league administrators alike.
The good news is some excellent endorsed programs exist to fully cover lacrosse teams. Let’s explore the options so you can make an informed decision to keep your players and team protected on the field.
Overview of USA Lacrosse endorsed insurance programs
As the national governing body for lacrosse, USA Lacrosse aims to provide affordable, comprehensive coverage for teams and leagues across the country. They’ve partnered with two major insurance providers to offer endorsed plans:
- Bollinger insurance program
- USA Football national insurance program
These plans were created specifically for lacrosse and provide broad coverage for leagues, teams, coaches, officials, and even field owners. The two options have slight differences, which we’ll explore shortly.
Bollinger insurance program details and coverage
The USA Lacrosse/Bollinger program is administered by K&K Insurance and underwritten by Nationwide. It provides both General Liability and Accident Medical coverage.
The General Liability protects against lawsuits from third party bodily injury or property damage claims. It covers lacrosse-related activities like games, practices, camps, clinics, meetings, uniform fittings, fundraisers, award banquets, parades, concessions, and more.
It provides protection for team coaches, officials, administrators, and volunteers. And importantly, coverage extends to field and facility owners who rent out their space.
The Accident Medical coverage functions similarly to health insurance, helping pay medical bills from injuries sustained during covered athletics. Standard policy benefits are $100,000 but higher limits are available.
USA Football national insurance program options
The USA Football insurance program is administered by Sadler Sports and underwritten by Gerber Life. Like the Bollinger plan, it bundles General Liability and Accident coverage.
An advantage here is flexibility. Teams can choose from multiple Accident Medical policy options with benefit limits ranging from $25,000 to $250,000. And you can customize the General Liability limits as needed for your team.
An additional benefit is Participant Legal Liability coverage, protecting coaches and administrators against negligence claims. This provides an extra layer of protection.
Explanation of general liability and accident insurance
As we’ve seen, General Liability and Accident coverage go hand-in-hand for lacrosse teams. But what do these types of insurance really cover?
General Liability insurance protects against financial loss from third party bodily injury, medical expenses, property damage, and personal injury claims like libel or slander. Lawsuits from spectators, facility/field owners, and outside parties would fall under the General Liability policy.
Accident coverage helps pay for the insured athletes’ medical treatment and rehabilitation for injuries suffered during covered athletic activities. Things like emergency room visits, surgeries, physical therapy, prescriptions, and follow-up care are included.
Importance of injury and liability protection for leagues
While no one likes thinking about worst-case scenarios, liability and accident coverage truly protects teams in the event of a serious accident or claim. Their importance simply can’t be overstated.
One lacrosse parent recounted a collision at an elite recruiting tournament that led to a brain injury. The injured player’s medical bills topped $150,000. Without proper insurance, this could have been financially devastating.
Comprehensive coverage also protects the future of youth sports programs. Rising insurance costs have forced many towns and schools to cut athletic programs. Having sound risk management makes leagues sustainable over the long run.
Affordable insurance rates for lacrosse clubs and teams
Thanks to the buying power of national organizations like USA Lacrosse, teams can access top-tier coverage at affordable rates. Costs vary based on factors like number of teams/participants, coverage levels chosen, and claims history.
But in general, expect yearly premiums from $300-$800 for youth teams and $800-$2,000+ for elite travel teams. Many league administrators pass the cost along in player registration fees.
Considering a single injury could exceed $100,000, this is a worthwhile investment that protects players, coaches, and the longevity of the team.
Coverage for practices, games, and tournaments
A common misconception is insurance only covers sanctioned games. In reality, robust policies like those endorsed by USA Lacrosse encompass all lacrosse activities.
Coverage extends to practices, scrimmages, tournaments, team travel, meetings, fundraising events, and more. Players don’t have to worry about gaps in protection.
Protecting coaches, officials, and administrators
Equally as important as covering athletes is extending protection to coaches, officials, and team administrators. Like players, these individuals face risks on the field.
Coaches can be sued for negligence in injury claims. Officials make judgement calls and occasionally errors. And league administrators handle equipment, maintain facilities, and make personnel decisions.
Comprehensive policies account for these risks and include key parties under the liability umbrella. USA Lacrosse partner plans were designed specifically with this in mind.
Insuring your lacrosse facility or field
Insuring teams is only half the equation. As an owner or operator of a lacrosse facility or field, you face substantial risks by allowing athletics on your premises.
Top lacrosse insurance plans explicitly extend General Liability coverage to rented premises used for sanctioned activities. This protects owners from potentially large legal claims.
Be sure to verify this component so your assets are covered. Also consider separate field or property insurance for ultimate protection.
Comparing plans: deductibles, limits, exclusions
While the USA Lacrosse endorsed programs offer comprehensive protection, some key variables differentiate the plans.
For General Liability coverage, Bollinger offers limits up to $2 million per occurrence, while USA Football goes up to $5 million. Deductibles range from $0 to $2,500 across the plans.
For Accident Medical, USA Football has more flexibility in limits, with options from $25k to $250k. Deductibles span from $0 to $1,000.
Exclusions exist as well, like injuries during unsanctioned events or high-risk activities like mountain climbing. Be sure to read policies closely and ask brokers about grey areas.
Filing claims if injuries or accidents occur
Should an accident occur, reporting it quickly and accurately is key. Time limits exist for filing claims, so don’t delay. Provide documents, medical records, and a full accounting of the incident.
For General Liability claims, alert your provider of any lawsuits or legal proceedings. They will need documentation served and details on the attorneys involved.
Having proper paperwork and following protocols will smooth the claims process. Lean on your broker for guidance in navigating the system.
Peace of mind from comprehensive coverage
At the end of the day, insurance provides peace of mind and financial protection your lacrosse club needs to thrive. Players can compete all out knowing they are covered.
And coaches can focus on skill development rather than worrying about legal exposures or injuries leaving families in financial crisis.
With the right coverage, you can enjoy the sport you love and create lifelong memories through healthy competition.
How to get quotes and apply for team insurance
Ready to secure coverage and protect your lacrosse club or team? Here are some tips for getting started:
- Check if your league or program already provides insurance. Many build it into registration fees.
- Decide which coverages and limits you need based on team activities.
- Contact USA Lacrosse partner brokers listed on their website for quotes.
- Provide details on teams, participants, and usage of rented fields/facilities.
- Compare rates and coverage from multiple providers.
- Ask brokers for explanations of exclusions or limitations.
- Purchase insurance well before your season begins to avoid gaps.
- Save copies of your policies and declarations for future reference.
With a reputable broker and USA Lacrosse endorsed program, you can gain top-tier protection at affordable rates. Your club will be covered and ready for a great season!
Overview of USA Lacrosse endorsed insurance programs
When it comes to protecting your lacrosse club, going with an endorsed program from USA Lacrosse is the way to go. These plans were designed hand-in-hand with lacrosse in mind, not just adapted from general sports insurance.
The two main options are through Bollinger and USA Football. Both bundle General Liability and Accident Medical, but have some differences.
Bollinger offers robust occurrence-based coverage via Nationwide, while USA Football uses Sadler Sports and Gerber Life for more flexible claims-made policies. Limits, deductibles, and add-ons vary across the board.
For most teams, either endorsed program will suffice. But it’s worth comparing rates and digging into the fine print to ensure optimal protection.
Why work through USA Lacrosse?
As the sport’s national governing body, USA Lacrosse has tremendous leverage to negotiate discounted premiums from top providers. This makes coverage more affordable for teams and leagues.
They also mandate appropriate coverage minimums for their sanctioned events. This ensures a consistent layer of protection for participants across the country.
USA Lacrosse also provides helpful risk management materials and trims legal exposures through their rules committees. This further reduces insurance costs.
Key points of Bollinger vs. USA Football plans
When evaluating the Bollinger and USA Football options, keep these key differences in mind:
- Bollinger uses occurrence policies while USA Football uses claims-made.
- Bollinger offers higher per-occurrence liability limits.
- USA Football has more Accident Medical limit options.
- USA Football includes participant legal liability coverage.
- Bollinger rates may be more competitive for larger clubs.
Consult with brokers to determine the best value based on your team’s size, activities, and risk tolerance.
Explanation of general liability and accident insurance
General liability and accident medical insurance are the two pillars of essential lacrosse team coverage. But what exactly do they protect against?
General liability insures against financial loss from claims by third parties alleging bodily injury, property damage, personal injury, or other covered claims from your lacrosse operations.
For example, if a stray shot breaks a facility’s window, their GL policy responds. Or if a player sued your league for a serious injury, GL would provide legal defense and settlement dollars.
Accident coverage pays medical expenses for injured participants directly. So if a player gets concussed or tears an ACL in practice, their policy helps cover medical bills and rehab costs.
Together, these coverages protect your most important assets – your players, coaches, and the club itself. Don’t operate without them.
Do we really need insurance for practices?
Absolutely! In fact, many serious injuries occur during practices rather than games. Protection is just as important on the practice field as game day.
Maybe even more so. Without refs, players may be more aggressive. And coaches often push players harder preparing for competition. Fatigue leads to mistakes and collisions.
You still have the same liability for safety of participants. Don’t risk massive bills from practice incidents. Get insured!
What about representative teams and travel?
Another key coverage point is extending protection wherever your teams go to compete. Tournaments, travel, and representing your club all require thorough insurance.
USA Lacrosse partner policies are designed for this purpose. They cover sanctioned activities wherever they occur, knowing lacrosse entails frequent travel.
Just provide details on locations and confirm coverage with your provider before heading out of town. Better safe than sorry!
Protecting coaches, officials, and administrators
Players rightfully receive focus when discussing lacrosse insurance, but protecting coaches, officials, and administrators is equally crucial.
These individuals face increased scrutiny in today’s ultra-competitive sports landscape. Margins are razor thin, so tensions run high.
One error by a ref or perceived mistake by a coach can generate angry backlash. And league admin decisions like roster moves spark disputes.
Top-notch policies account for this by including key personnel under the liability umbrella right next to players. Leave no one exposed!
What does participant legal liability cover?
Participant legal liability takes protection a step further by shielding coaches and admins from negligence claims. It covers legal costs if sued for failure to supervise athletes properly.
For example, if an injured player alleged improper medical response or unsafe conditions as the cause, participant liability helps defend against litigation in that scenario.
This provides invaluable peace of mind to coaches and volunteers who give their time for the benefit of the players.
Do team doctors need their own coverage?
Absolutely. While your lacrosse insurance should cover doctors you directly employ, most teams utilize volunteer or independent doctors. These medical professionals need their own malpractice insurance.
Require proof of coverage from any doctors working with your teams. Don’t risk liability for their errors or omissions. Safety first!
How to get quotes and apply for team insurance
Ready to get your club insured for the upcoming season? Here’s a game plan for making it happen:
- Determine necessary coverage types and minimum limits based on your activities.
- Check USA Lacrosse’s website for a list of endorsed brokers.
- Contact 2-3 brokers to explain your needs and get quotes.
- Provide details on participants, locations, travel plans, etc.
- Compare premiums, exclusions, deductibles, and ease of claims.
- Choose the plan that best fits your budget yet still provides robust coverage.
- Complete all required applications and forms fully and honestly.
- Pay premiums on time to activate policies without gaps.
- Confirm policy documents and declaration pages are accurate.
With smart shopping and USA Lacrosse’s guidance, you’ll gain top-tier protection to play confidently this season. Let the games begin!
Bollinger insurance program details and coverage
One of the premier options for protecting your lacrosse club is the USA Lacrosse/Bollinger program. Offered through K&K Insurance and underwritten by Nationwide, it provides broad coverage scaled for the sport.
The Bollinger policy has two main components – General Liability and Accident Medical. But what exactly do these encompass for your team?
The General Liability piece covers third party bodily injury, property damage, and personal injury claims stemming from lacrosse activities. Lawsuits from spectators, vendors, or facility owners would fall under GL.
GL limits range from $1 million to $2 million per occurrence with options for higher. It covers premises liability for rented fields, participant liability, and products/completed operations.
The Accident Medical functions like health insurance to cover injuries to insured participants. It helps pay for expenses like ER visits, surgeries, hospital stays, rehab, prescriptions and more.
Standard Accident Medical limits are $100k but increase up to $250k with added premiums. Deductibles range from $0 to $2,500.
Core strengths of Bollinger lacrosse insurance
The Bollinger program shines with:
- Occurrence-based policies from a top carrier
- Limited exclusions for better coverage
- Insurance specifically scaled for lacrosse
- Broad definition of covered activities
- Affordable premiums through USA Lacrosse
It’s designed for straightforward protection rather than nailing teams on technicalities.
What does “occurrence form” mean?
Occurrence-based coverage means policies cover claims stemming from incidents within the policy period regardless of when claims arise. This offers stronger protection compared to claims-made policies.
For example, if an injury occurs but isn’t discovered until years later, your occurrence-based GL would still respond even if no longer a policyholder.
This matters for latent injuries and provides peace of mind your historic risks are covered.
USA Football national insurance program options
The other excellent choice within the USA Lacrosse umbrella is the USA Football insurance program. While similar to Bollinger, some key differences exist.
The USA Football plan uses Sadler Sports as the administrator along with Gerber Life Insurance for underwriting. And they offer more flexibility in customizing limits.
General Liability options range from $1 million up to $5 million per occurrence. And Accident Medical goes from $25,000 to $250,000 to dial in specific needs.
Deductibles scale from $0 to $2,500 for GL and $0 to $1,000 for Accident. Higher deductibles bring lower premiums.
Comparing Bollinger and USA Football
Weighing the Bollinger and USA Football plans:
- Bollinger GL limits go up to $2 million per occurrence vs. $5 million for USA Football.
- Bollinger uses occurrence-based forms while USA Football is claims-made.
- Bollinger rates are generally lower for larger clubs.
- USA Football includes participant legal liability coverage.
For most lacrosse teams, either will provide sufficient protection. Compare costs and scoop for your situation.
Bundling insurance for multi-sport clubs
If your athletic club hosts multiple sports, bundling plans through a single provider may make sense. Just ensure lacrosse is explicitly included and covered activities defined.
Bollinger offers a multi-sport accident program. And USA Football allows “universal play” insurance covering non-tackle sports. Discuss options with your broker.
The right policy provides peace of mind so you can play all out. Research diligently and choose what’s best for your club!
USA Football national insurance program options
In addition to the Bollinger insurance plan, USA Lacrosse endorses the USA Football national insurance program for lacrosse clubs. This provides another excellent option for protection.
The USA Football plan is administered by Sadler Sports Insurance and underwritten by Gerber Life Insurance Company. It bundles General Liability and Accident Medical coverage.
Policy limits allow more customization than the Bollinger program. GL options range from $1 million up to $5 million per occurrence. Accident Medical spans from $25,000 to $250,000.
Deductibles also scale from $0 to $2,500 for GL claims and $0 to $1,000 for Accident expenses. Going higher on deductibles reduces premiums.
Core advantages of USA Football insurance
Key strengths of the USA Football plan include:
- Flexibility in limits and deductibles
- Participant legal liability protection
- Option for higher $5M GL limits
- Claims-made policy form
- Generally lower rates for smaller clubs
With the ability to tailor coverage, you can really dial it in for your specific club’s needs and budget.
Comparing USA Football and Bollinger
Weighing the two primary choices:
- USA Football offers higher GL limits ($5M vs $2M per occurrence for Bollinger)
- Bollinger uses occurrence-based forms while USA Football policies are claims-made
- Bollinger rates can be lower for larger clubs
- USA Football has more Accident Medical limit options
Chat with brokers to see competitive quotes. Either provides strong lacrosse-specific protection.
Insuring your lacrosse facility or field
When allowing any organized athletics on your property, having insurance protection is a must. Lacrosse poses substantial risks to facility and field owners.
Errant shots can break windows or lights. Collisions may damage turf or fencing. And serious injuries often lead to lawsuits targeting owners.
Top lacrosse insurance policies account for this by extending General Liability to rented or donated premises used for sanctioned activities.
This protects owners against potentially massive legal judgments. Always confirm this component is explicitly included before allowing teams on your property.
What about liability waivers?
While waiving rights can help shield against claims, relying solely on liability waivers is asking for trouble. They often don’t hold up in court depending on specific circumstances.
Sound insurance coverage is still crucial. Work with an attorney to craft waivers that flag risks and release you from inherent dangers, but back it up with proper GL policies just in case.
Additional field and property insurance
Besides being named under teams’ GL for injury claims, owners may consider separate field and property insurance. This covers first-party damage to your assets.
For example, if lighting equipment is damaged in a storm or bleachers collapse, field and property insurance helps pay for repairs or replacement without relying on legal claims.
Discuss options with your broker to be sure your facility is fully protected from all angles.
Comparing plans: deductibles, limits, exclusions
When evaluating USA Lacrosse endorsed insurance plans, key variables to analyze include:
- Per occurrence limits for General Liability (Bollinger $2M max vs. $5M for USA Football)
- Range of deductible options (typically $0 – $2,500)
- Accident Medical limits and deductibles
- Covered lacrosse activities and any exclusions
- Claims-made vs. occurrence-based policies
Drilling into these details ensures you gain the robust, tailored protection your club requires. Don’t settle for gaps in coverage or insufficient limits.
Being honest with brokers
One critical tip when applying is representing your teams and activities accurately. This ensures proper coverage.
Disclose injuries, lawsuits, or major claims from past years. List all participants and location details. Hide nothing from brokers.
Attempting to lower premiums through omission will only void protection when it matters most. Honesty pays off in the long run.
Verifying coverage details
Upon approving applications, brokers will issue formal policy declarations outlining coverages, limits, deductibles and exclusions.
Review documents carefully to confirm they match your original requests and needs. Flag any discrepancies immediately and have corrected.
Don’t assume you’re covered. Verify every detail so lacrosse season goes smoothly.
Explanation of general liability and accident insurance
Two key forms of coverage your lacrosse club needs are general liability and accident medical insurance. But what exactly do these protect against?
General liability insures against third party claims alleging bodily injury, property damage, or personal injury stemming from your lacrosse operations and activities.
For example, if a stray shot breaks a stadium light and the venue sues, their claim would fall under your GL policy’s coverage.
Or if a participant sued for a serious injury suffered at a team event, GL would pay legal defense costs and covered lawsuit damages.Accident medical coverage pays expenses to treat injuries directly suffered by insured participants, like players, coaches and officials. It functions similarly to health insurance.
So if a player tears an ACL at practice and needs surgery and rehab, accident coverage helps pay their medical bills.
Common GL claims scenarios
General liability protects in situations like:
- Spectator hit by an errant ball or stick
- Injury due to unsafe field conditions
- Patron slips and falls at team fundraiser
- Property damage from post-game celebrations
- Sideline incident with referees or opposing fans
Sound GL limits ensure you won’t go bankrupt from an unforeseen accident.
Why accident coverage matters
Considering lacrosse athletes are young and often still on family plans, why does accident insurance matter?
Two key reasons:
- Fills gaps if family insurance won’t cover sports injuries
- Avoids tapping parents’ high deductibles or out-of-pocket costs
This keeps medical costs from derailing families’ budgets or kids’ playing careers.
Importance of injury and liability protection for leagues
It’s tempting to downplay risks when organizing youth sports. But ignoring liability realities can have disastrous consequences.
Lawsuits and uninsured injuries threaten a league’s survival. One serious incident alone results in five- or six-figure costs.
With proper insurance, your club continues operations and serving the community. Without it, you risk insolvency from a single accident.
Rising insurance costs
Insurance premiums continue marching higher across all sectors, sports included. This cripples budgets for many teams and rec leagues.
But protection remains mandatory. USA Lacrosse’s bargaining power helps take the sting out of rate hikes.
Review premium financing options if needed. Efforts like fundraising and sponsorship can help defray costs over time as well.
The alternative is unacceptable
What’s the alternative to proper lacrosse insurance? Shutting down your program.
Most facilities will not rent space without GL coverage minimums. And ethical questions loom without injury protection.
View premiums as an investment in your club’s future. There is no upside to risking disaster to save a few dollars today.
Affordable insurance rates for lacrosse clubs and teams
Thanks to USA Lacrosse’s standing in the sport, clubs gain access to top-tier coverage at affordable rates. Premiums vary based on:
- Number of participants
- Claims history
- Policy limits and deductibles
- Youth vs. elite teams
- Geographic location
Typical ranges:
- Youth rec league – $300 to $800 yearly
- Competitive travel team – $800 to $2,000+
Considering a single severe injury often exceeds $100k, premium costs are reasonable for robust protection.
Comparing carriers
When quoting, look at both USA Lacrosse-endorsed options – Bollinger and USA Football. Weigh factors like:
- Policy types (occurrence vs. claims-made)
- Ratings strength
- Customer service reputation
- Ease of filing claims
Meet with brokers to analyze your unique situation before selecting the best value.
Don’t skimp on coverage
When evaluating premium outlays, resist the urge to skimp on limits or key coverages to save a few dollars. Doing so leaves major gaps.
Lock down adequate GL, accident medical, participant liability, premises coverage and more. Complete protection brings peace of mind.
Importance of injury and liability protection for leagues
Organizing youth lacrosse comes with big responsibility. Avoiding discussion of risks is negligent. Injury and liability exposures threaten your league’s survival.
Consider the financial fallout from just one serious incident:
- $50,000 for initial hospital treatment
- $75,000+ for surgeries and ongoing care
- $25,000 for lawyer fees, even if no lawsuit filed
And those figures assume no permanent disability requiring lifetime assistance. Or multi-million dollar settlement if sued.
This bankrupts families without proper insurance. And cripples your league’s finances through legal defense alone.
Why insurance rates are rising
Youth sports insurance continues getting more expensive across all sports. Factors driving rate increases include:
- Rise in liability lawsuits
- Increase in medical costs
- Larger injury claim payouts
- Insurers exiting sports market
For many leagues, just a few years ago policies were 25-50% lower. Protecting programs requires adjusting budgets.
Making coverage a priority
With insurance eating bigger chunks of budgets, it’s tempting to scale back. But doing so is unwise.
Proper injury and liability protection ensures your league’s survival. This enables serving the community for years.
Explore ways to creatively fund premiums like sponsorships, fundraising, and rolling costs into registration fees.
Coverage for practices, games, and tournaments
At all levels, a common misconception is insurance only covers sanctioned games. In reality, robust policies like those endorsed by USA Lacrosse encompass the full range of lacrosse activities.
Protection extends to practices, scrimmages, team travel, fundraising events, meetings, tournaments, and more. There are no gaps barring excluded activities.
Why insure practices?
Some assume practice carries lower risk than games. But many serious injuries actually occur in practice due to:
- More full contact without officials
- Trying new drills and plays
- Fatigue leading tocollisions
- Pushing players’ limits preparing for games
Don’t leave practice uncovered. Injuries on your watch still require response regardless of context.
Tournament and travel coverage
Tournaments and traveling for games are core parts of higher-level lacrosse. Robust insurance travels with the team.
Policies cover sanctioned activities wherever they occur. No need to notify insurers every trip.
Just report locations ahead of time at enrollment, so nothing slips through the cracks.
Comparing plans: deductibles, limits, exclusions
Key variables separating USA Lacrosse endorsed plans include:
- General liability per occurrence limits
- Accident medical benefit limits
- Plan deductibles
- Policy types – claims-made vs occurrence form
- Covered lacrosse activities and exclusions
Drilling into these details ensures you gain the right protection profile for your unique risk needs and budget.
Locking down adequate coverage
When comparing plans, focus first on securing sufficient coverage levels. Don’t penny pinch limits and leave gaps.
General liability requirements vary by venue, but $1 million per occurrence is usually minimum. Confirm other elements like participant liability, premises coverage, and products liability are included.
For accident medical, look for policies with possible benefits up to $250,000 to protect against catastrophic injuries.
Higher deductibles, lower premiums
Plans allow customizing deductibles to strike the right premium balance. Choose higher deductibles to reduce overall costs if able to cover small claims yourself.
Just ensure limits and core coverages still sufficiently protect assets. Don’t sacrifice proper protection solely to trim premium spending.
Affordable insurance rates for lacrosse clubs and teams
Thanks to USA Lacrosse’s standing and focus on risk management, clubs can access top-tier coverage at reasonable rates. Premiums vary based on factors like:
- Number of teams and participants
- Youth rec vs. elite travel focus
- Claims history and risk profile
- Policy types and limits
- Geographic location
Typical ranges:
- Youth rec league – $300 to $800 per year
- Competitive travel team – $800 to $2,000+
Compared to potential six-figure liability claims, premiums are inexpensive peace of mind.
Creative ways to fund premiums
Premium sticker shock is common among new teams and leagues. Ways to tackle costs include:
- Spread across registration fees
- Sponsorships and donations
- Fundraising events
- Payment plans
- Tap cash reserves upfront if able
Insurance enables playing at all. Make financing a team effort.
Shop brokers and carriers
To ensure affordable rates, compare quotes from multiple brokers and explore both USA Lacrosse carrier options – Bollinger and USA Football.
Weigh factors like financial strength, customer service, and claims experiences. Meet with reps to explain your specific needs.
Invest time upfront to secure the optimal program. Saving a few dollars today can cost big tomorrow.
Protecting coaches, officials, and administrators
Player safety rightfully receives top focus when discussing lacrosse insurance. But protecting coaches, officials, and league administrators is equally crucial.
These individuals dedicate time and passion to growing the sport. They deserve liability protection stemming from that role.
Comprehensive policies specifically name key personnel as insureds right next to players. Don’t leave them exposed.
What participant legal liability covers
For additional protection, some plans feature participant legal liability coverage. This covers defense costs if coaches or administrators face negligence lawsuits.
For example, if a player’s family alleged improper medical response after an injury, this policy would pay legal expenses even if no judgment awarded.
Without it, individuals risk bankruptcy defending themselves even from frivolous claims. It brings invaluable peace of mind.
Requiring volunteer waivers
Another layer of protection involves requiring liability waivers from coaches, referees, concession workers and any volunteers.
Well-crafted waivers demonstrate assuming inherent risks. This strengthens the liability shield if injuries or accidents occur.
Pair waivers with proper insurance for fullest protection. Don’t leave loyal volunteers hanging.
Insuring your lacrosse facility or field
By allowing organized athletics on your property, owners and operators accept substantial risks. Errant lacrosse balls and collisions cause damage.
And injuries inevitably happen, whether from poor maintenance or just incidental contact. Resulting lawsuits can be financially devastating without insurance.
Top lacrosse policies account for this by adding leased facilities under the liability umbrella. But additional coverage is wise.
Require teams carry and name your property
Leagues renting space must carry General Liability policies naming your business as additional insured. Confirm this before handing over keys.
Also require a minimum limit ($1 million per occurrence) to ensure sufficient coverage from their carrier.
Review their declaration page for proof. Don’t risk their gaps becoming your problem.
Explore supplemental coverage options
For fuller protection, explore supplemental field and property coverage beyond what teams provide.
This covers first-party damage to your assets should, say, lighting equipment fail or bleachers collapse. It provides direct compensation without the need to file claims against users.
Discuss options like premises liability, property insurance, and equipment coverage with your broker.
Coverage for practices, games, and tournaments
At all levels, a common misconception is lacrosse insurance only covers sanctioned games. But robust policies like those endorsed by USA Lacrosse actually encompass the full range of lacrosse activities.
Protection broadly extends to practices, scrimmages, team travel, fundraising events, meetings, tournaments, and more. There are no major gaps barring excluded high-risk activities.
Insuring intense practices
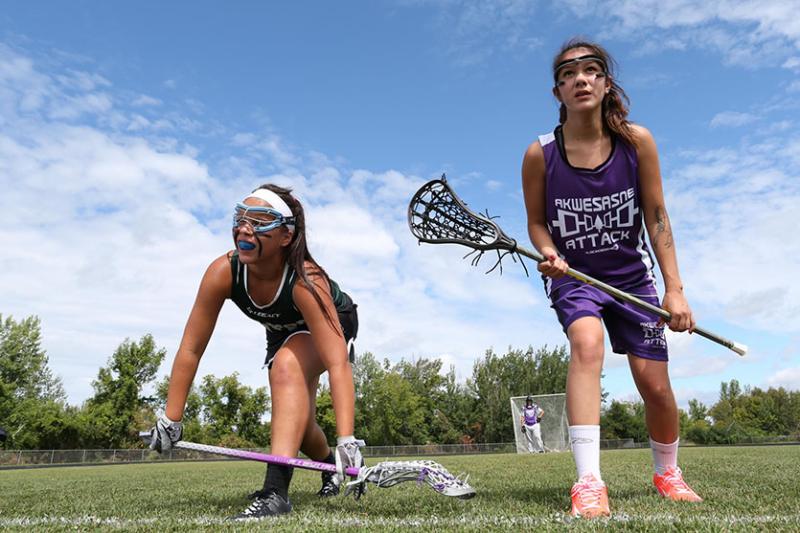
Some assume practices carry less risk than live games. But many serious injuries actually occur in practices due to:
- More intense contact without officials
- Trying new complex drills or plays
- Fatigue leading to collisions
- Pushing players to improve
Don’t leave practices uncovered just because they’re not “real” games. Injuries under your watch still require response regardless of context.
Tournament and travel coverage
Higher-level tournaments and travel are core parts of competitive lacrosse. Top insurance travels wherever the team goes.
Robust policies cover sanctioned activities wherever they occur, whether across town or across the country. No need to notify insurers every trip.
The key is disclosing locations you’ll visit during enrollment. Then you’re covered without gaps.
Comparing plans: deductibles, limits, exclusions
When evaluating insurance options, focus first on securing adequate coverage levels before pricing. Don’t sacrifice protection to trim premiums.
Key variables differentiating plans include:
- General liability limits per occurrence
- Accident policy benefit maximums
- Plan deductibles
- Covered lacrosse activities and exclusions
- Claims-made vs occurrence-based policies
General liability requirements
Most venues require $1 million per occurrence minimums. Higher limits of $2 million or more preferable for robust protection. Don’t cut limits to save a few dollars.
Ensure coverage includes elements like participant legal liability, medical payments, and rented premises. Review declarations closely for any gaps.
Injury costs add up quickly
For accident medical, aim for policies with potential benefits reaching $200k or more. Initial surgeries often exceed $100k alone for serious injuries like ligament tears.
The long road of rehab and physical therapy piles on costs. Don’t be penny wise but pound foolish skimping on injury coverage.
Insuring your lacrosse facility or field
By allowing organized athletics on your property, owners and operators accept substantial liability. Errant balls cause damage. Injuries inevitably happen.
Lawsuits from these incidents can be financially devastating without proper insurance. All it takes is one accident or injury to upend a business.
Require renters carry GL naming you
Leagues renting space must carry General Liability policies specifically naming your business as additional insured. Simply suggesting coverage is not enough.
Require a certificate of insurance proving solid GL limits before handing over keys. Review policy documents to confirm you’re truly protected.
Explore supplemental coverage options
For fuller protection beyond renters’ policies, explore supplemental field and property coverage through your own insurer.
This covers direct damage to your assets should equipment fail or structures like bleachers collapse. Pays your claims directly without pursuing renters’ policies.
Discuss options like premises liability, property insurance, and equipment coverage with your broker.
Filing claims if injuries or accidents occur
Should an accident or injury occur, prompt and accurate claim filing is critical. Missing deadlines jeopardizes coverage.
For liability claims, immediately alert your insurer of incidents and forward any legal documents received. Provide full details on the accident circumstances and parties involved.
For medical claims, submit required documents like exam notes, hospital bills, and invoices for treatments and devices. Keep thorough records.
Prepare documents and evidence
Have information like these ready for claim submission:
- Medical reports and billing documents
- Police reports, if applicable
- Photographs and video of damage
- Repair estimates or receipts
- Eyewitness accounts of the incident
Presenting a well-documented claim helps insurers process payments faster. Disorganization slows the workflow.
Appealing denied claims
If your claim gets denied, don’t panic. Start by requesting the exact rationale in writing from your insurer.
Evaluate if you have grounds for appeal based on extenuating circumstances or plan document language. Consult your broker for guidance navigating appeals.
With persistence and evidence, many denials get overturned. Don’t immediately accept a claim denial as the final word.
Protecting coaches, officials, and administrators
In lacrosse, player safety grabs headlines. But fully protecting coaches, officials, and league administrators is equally crucial.
These individuals dedicate huge time and passion growing the sport. They deserve insurance protection for that contribution.
Top-tier policies specifically name key personnel as insureds alongside players. Everyone is covered jointly.
Risks facing coaches
Coaches face scrutiny managing player health. Injuries bring accusations of negligence or poor training.
One lawsuit alone can bankrupt a coach even if no judgment awarded. Policies defend against frivolous claims.
Coaches also make judgement calls like holding players out of games. Parents sometimes sue over these decisions impacting kids’ futures.
Exposures for officials
Like coaches, officials face backlash over split-second decisions impacting games. Irate fans or parents can get aggressive.
Disgruntled teams may sue for lost scholarship opportunities if a key call goes against them. Officials need protection.
Even volunteer referees require coverage against lawsuits. Don’t have them assume unknown liability.
Insuring your lacrosse facility or field
By allowing organized athletics on your property, owners and operators accept substantial liability. Errant balls cause damage. Injuries inevitably happen.
Lawsuits from these incidents can be financially devastating without proper insurance. All it takes is one accident or injury to upend a business.
Require renters carry GL naming you
Leagues renting space must carry General Liability policies specifically naming your business as additional insured. Simply suggesting coverage is not enough.
Require a certificate of insurance proving solid GL limits before handing over keys. Review policy documents to confirm you’re truly protected.
Explore supplemental coverage options
For fuller protection beyond renters’ policies, explore supplemental field and property coverage through your own insurer.
This covers direct damage to your assets should equipment fail or structures like bleachers collapse. Pays your claims directly without pursuing renters’ policies.
Discuss options like premises liability, property insurance, and equipment coverage with your broker.
Filing claims if injuries or accidents occur
Should an accident or injury occur, prompt and accurate claim filing is critical. Missing deadlines jeopardizes coverage.
For liability claims, immediately alert your insurer of incidents and forward legal documents received. Provide full accident details and parties involved.
For medical claims, submit required documents like exam notes, hospital bills, and invoices for treatments and devices. Keep thorough records.
Have these documents ready
Prepare information like:
- Medical reports and billing records
- Police reports, if applicable
- Photographs and video documenting damage
- Repair estimates or receipts
- Eyewitness accounts of the incident
Well-documented claims help insurers process payments faster. Disorganization slows the workflow.
Don’t accept initial claim denials
If your claim gets denied, first request the exact rationale in writing from your insurer. Evaluate if grounds for appeal exist based on plan language or circumstances.
Consult your broker for guidance navigating appeals. With persistence and evidence, many denials get overturned. Don’t immediately accept a denial as final.
Insuring your lacrosse facility or field
By allowing organized athletics on your property, owners and operators accept substantial liability. Errant lacrosse balls cause damage. Injuries inevitably happen.
Lawsuits from these incidents can be financially devastating without proper insurance. All it takes is one accident or injury to upend a business.
Require renters carry GL naming you
Leagues renting space must carry General Liability policies specifically naming your business as additional insured. Simply suggesting coverage is not enough.
Require a certificate of insurance proving solid GL limits before handing over keys. Review policy documents to confirm you’re truly protected.
Explore supplemental coverage options
For fuller protection beyond renters’ policies, explore supplemental field and property coverage through your own insurer.
This covers direct damage to your assets should equipment fail or structures like bleachers collapse. Pays your claims directly without pursuing renters’ policies.
Discuss options like premises liability, property insurance, and equipment coverage with your broker.
Comparing plans: deductibles, limits, exclusions
When evaluating insurance options, focus first on securing adequate coverage levels before pricing. Don’t sacrifice protection to trim premiums.
Key variables differentiating plans include:
- General liability limits per occurrence
- Accident policy benefit maximums
- Plan deductibles
- Covered lacrosse activities and exclusions
- Claims-made vs occurrence-based policies
General liability requirements
Most venues require $1 million per occurrence minimums. Higher limits of $2 million or more preferable for robust protection. Don’t cut limits to save a few dollars.
Ensure coverage includes elements like participant legal liability, medical payments, and rented premises. Review declarations closely for any gaps.
Injury costs add up quickly
For accident medical, aim for policies with potential benefits reaching $200k or more. Initial surgeries often exceed $100k alone for serious injuries like ligament tears.
The long road of rehab and physical therapy piles on costs. Don’t be penny wise but pound foolish skimping on injury coverage.
Filing claims if injuries or accidents occur
Should an accident or injury occur, prompt and accurate claim filing is critical. Missing deadlines jeopardizes coverage.
For liability claims, immediately alert your insurer of incidents and forward legal documents received. Provide full accident details and parties involved.
For medical claims, submit required documents like exam notes, hospital bills, and invoices for treatments and devices. Keep thorough records.
Prepare documents and evidence
Have information like these ready for claim submission:
- Medical reports and billing documents
- Police reports, if applicable
- Photographs and video of damage
- Repair estimates or receipts
- Eyewitness accounts of the incident
Well-documented claims help insurers process payments faster. Disorganization slows the workflow.
Don’t accept initial claim denials
If your claim gets denied, first request the rationale in writing from your insurer. Evaluate if grounds for appeal based on plan language or circumstances.
Consult your broker for guidance navigating appeals. With persistence and evidence, many denials get overturned. Don’t immediately accept a denial as final.
Comparing plans: deductibles, limits, exclusions
When evaluating insurance options, focus first on securing adequate coverage levels before pricing. Don’t sacrifice protection to trim premiums.
Key variables differentiating plans include:
- General liability limits per occurrence
- Accident policy benefit maximums
- Plan deductibles
- Covered lacrosse activities and exclusions
- Claims-made vs occurrence-based policies
General liability requirements
Most venues require $1 million per occurrence minimums. Higher limits of $2 million or more preferable for robust protection. Don’t cut limits to save a few dollars.
Ensure coverage includes elements like participant legal liability, medical payments, and rented premises. Review declarations closely for any gaps.
Injury costs add up quickly
For accident medical, aim for policies with potential benefits reaching $200k or more. Initial surgeries often exceed $100k alone for serious injuries like ligament tears.
The long road of rehab and physical therapy piles on costs. Don’t be penny wise but pound foolish skimping on injury coverage.
Filing claims if injuries or accidents occur
Should an accident or injury occur, prompt and accurate claim filing is critical. Missing deadlines jeopardizes coverage.
For liability claims, immediately alert your insurer of incidents and forward legal documents received. Provide full accident details and parties involved.
For medical claims, submit required documents like exam notes, hospital bills, and invoices for treatments and devices. Keep thorough records.
Prepare documents and evidence
Have information like these ready for claim submission:
- Medical reports and billing documents
- Police reports, if applicable
- Photographs and video of damage
- Repair estimates or receipts
- Eyewitness accounts of the incident
Well-documented claims help insurers process payments faster. Disorganization slows the workflow.
Don’t accept initial claim denials
If your claim gets denied, first request the rationale in writing from your insurer. Evaluate if grounds for appeal based on plan language or circumstances.
Consult your broker for guidance navigating appeals. With persistence and evidence, many denials get overturned. Don’t immediately accept a denial as final.
Conclusion: Get your team insured for lacrosse season
Coverage allows enjoying the sport you love while protecting against financial disasters. Players can compete all out knowing they’re covered if incidents occur.
And coaches gain peace of mind focusing on development rather than legal risks or uncovered injuries derailing families.
With the right lacrosse insurance plan secured through USA Lacrosse’s guidance, your club and community are protected. Have a great season!
Filing claims if injuries or accidents occur
Should an accident or injury occur, prompt and accurate claim filing is critical. Missing deadlines jeopardizes coverage.
For liability claims, immediately alert your insurer of incidents and forward legal documents received. Provide full accident details and parties involved.
For medical claims, submit required documents like exam notes, hospital bills, and invoices for treatments and devices. Keep thorough records.
Prepare documents and evidence
Have information like these ready for claim submission:
- Medical reports and billing documents
- Police reports, if applicable
- Photographs and video of damage
- Repair estimates or receipts
- Eyewitness accounts of the incident
Well-documented claims help insurers process payments faster. Disorganization slows the workflow.
Don’t accept initial claim denials
If your claim gets denied, first request the rationale in writing from your insurer. Evaluate if grounds for appeal based on plan language or circumstances.
Consult your broker for guidance navigating appeals. With persistence and evidence, many denials get overturned. Don’t immediately accept a denial as final.
Conclusion: Get your team insured for lacrosse season
Coverage allows enjoying the sport you love while protecting against financial disasters. Players can compete all out knowing they’re covered if incidents occur.
And coaches gain peace of mind focusing on development rather than legal risks or uncovered injuries derailing families.
With the right lacrosse insurance plan secured through USA Lacrosse’s guidance, your club and community are protected. Have a great season!
Key Takeaways
Here are some key tips to recap on securing proper lacrosse insurance:
- Work with USA Lacrosse endorsed brokers and carriers
- Require General Liability and Accident Medical at minimum
- Review policy documents carefully for gaps in coverage
- Report incidents promptly to avoid claim denials
- Document injuries thoroughly just in case
- Appeal any claim denials you believe unwarranted
- Consult brokers for guidance navigating policies
With smart preparation, wise coverage choices, and quick response when needed, your season will be smooth sailing. Enjoy the competition and exercise safely!
Peace of mind from comprehensive coverage
At the end of the day, lacrosse insurance provides invaluable peace of mind so your club can thrive. Players can compete with confidence knowing risks are covered.
And coaches can focus on development, not legal hazards or financial crisis from uncovered injuries. Comprehensive protection lets you enjoy the sport.
Safeguarding players’ futures
For families, a disabling injury could mean mountains of medical debt or lost college scholarship chances without proper coverage.
But full accident medical and liability protection ensure kids’ futures remain bright even if the worst occurs on the field.
Empowering coaches and refs
Quality insurance also empowers coaches and officials to support athletes to the fullest without fear of legal repercussions.
Participant liability coverage has their back if accusations arise over tough calls or injury response. They can lead confidently.
Key Takeaways
Here are some key tips to recap on securing proper lacrosse insurance:
- Work with USA Lacrosse endorsed brokers and carriers
- Require General Liability and Accident Medical at minimum
- Review policy documents carefully for gaps in coverage
- Report incidents promptly to avoid claim denials
- Document injuries thoroughly just in case
- Appeal any claim denials you believe unwarranted
- Consult brokers for guidance navigating policies
With smart preparation, wise coverage choices, and quick response when needed, your season will be smooth sailing. Enjoy the competition and exercise safely!
Final Thoughts
By securing the right lacrosse insurance for your teams and leagues, you create a foundation for success and enjoyment.
Robust protection gives participants confidence to play all out, coaches the ability to challenge athletes, and administrators freedom to take strategic risks.
USA Lacrosse’s trusted guidance and carrier partnerships make coverage accessible and affordable at all levels. Invest wisely and have a great upcoming season!
How to get quotes and apply for team insurance
Ready to secure coverage and protect your lacrosse club or team? Here are some tips for getting started:
- Check if your league already provides group insurance. Many build it into fees.
- Decide which coverages and limits you need based on team activities.
- Contact USA Lacrosse partner brokers listed on their website for quotes.
- Provide details on teams, participants, and usage of rented fields/facilities.
- Compare rates and coverage from multiple providers.
- Ask brokers to explain policy exclusions or limitations.
- Purchase insurance well before your season begins to avoid gaps.
- Save copies of your policies and declarations for future reference.
With a reputable broker and USA Lacrosse endorsed program, you can gain top-tier protection at affordable rates. Your club will be ready for a great season!
Allow time for underwriting
One key point is applying for coverage 1-2 months before your season starts. The underwriting process takes time, so don’t risk going uncovered.
Submitting applications early also allows adjusting plans if needed before lacrosse activities commence.
Provide full details
Accuracy matters – give brokers a full picture of your teams, ages, past claims, and locations. Omitting details could void protection later.
Discuss any concerns transparently upfront to ensure the right program. Honesty pays off when claims arise.
Key Takeaways
Here are some key tips to recap on securing proper lacrosse insurance:
- Work with USA Lacrosse endorsed brokers and carriers
- Require General Liability and Accident Medical at minimum
- Review policy documents carefully for gaps in coverage
- Report incidents promptly to avoid claim denials
- Document injuries thoroughly just in case
- Appeal any claim denials you believe unwarranted
- Consult brokers for guidance navigating policies
With smart preparation, wise coverage choices, and quick response when needed, your season will be smooth sailing. Enjoy the competition and exercise safely!
Final Thoughts
By securing the right lacrosse insurance for your teams and leagues, you create a foundation for success and enjoyment.
Robust protection gives participants confidence to play all out, coaches the ability to challenge athletes, and administrators freedom to take strategic risks.
USA Lacrosse’s trusted guidance and carrier partnerships make coverage accessible and affordable at all levels. Invest wisely and have a great upcoming season!
Conclusion: Get your lacrosse team insured this season
Having proper insurance coverage allows you to enjoy the sport you love while protecting against financial disasters. Players can compete all out knowing they’re covered if accidents occur.
Coaches gain peace of mind focusing on development rather than legal risks or uncovered injuries derailing families.
With the right lacrosse insurance plan secured through USA Lacrosse’s trusted guidance and carrier partnerships, your club and community are protected. Don’t play games with safety – get insured before stepping on the field.
Safeguarding your lacrosse legacy
At the end of the day, protection is about more than avoiding lawsuits or medical bills. It’s about enabling the sport to thrive for future generations.
With comprehensive coverage, you create a sustainable program that families can enjoy for years to come. That’s the true win.
Now get out and play!
You’ve worked hard to build something special. Capturing the excitement of competition, the bonds of teamwork, and the lessons of perseverance.
So protect that investment. Then get out and play hard this season! One team, one goal – insured and uncompromising. See you on the field!